House hunt stories: He dreamed of a South End brownstone for 12 years. It took 90 days of chaos to get one.

Home Buying
Boston resident Kris Moore shares the ups and downs that led to condo ownership
Twelve years ago, not long after Kris Moore moved to Boston, he settled on a real estate goal as he explored his new city: “Someday I want to live in a brownstone in the South End,” he said.
Last spring, the dream came true. The 40-year-old, who works at a downtown law firm, finally got his keys after a bidding war with 12 offers, a seller who could legally walk away at any moment, and a brief, unplanned stint as a landlord to two frustrated tenants.
“I kept taking on added risk and complexity because the fundamentals of the place were strong, even if the process itself was stressful,” Moore said.
Budget: $750,000
Search radius: South End or bust.
The find: a 711-square-foot, two-bedroom, parlor-level condo near West Canton Street and Columbus Avenue, listed at $700,000 in December 2024.
Purchase price: $780,000.
The challenges:
· Went over budget; high interest rates
· Sellers were rolling the proceeds into a 1031 exchange, which can allow deferring capital gains taxes on sales of investment properties
· Unit was tenant-occupied
· Historic brownstone required renovations

Finding the perfect place — and navigating bumps in the road
Moore was no rookie. He previously owned a condo on the East Side of South Boston for nearly three years, sold it in 2021, and set aside the profit. After several years of renting in the South End, he decided in the fall of 2024 that he was ready to buy again. His lease ran through the spring, so there was no rush. The plan was simply to hit open houses through the winter and get a feel for what his money could buy.
At first, the answer was sobering. His first stop was a one-bedroom condo on Warren Avenue in the low $700,000s that needed work. But open house number two was the one.
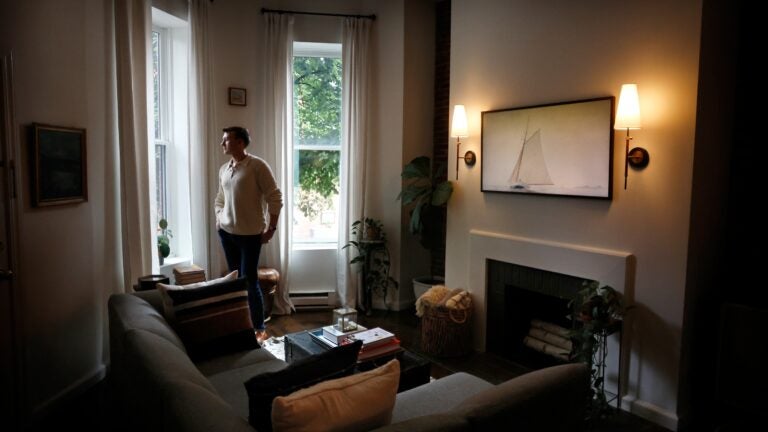
The two-bedroom condo had been a rental for years, and it showed. The listing photos were dim and the tenants’ oversized furniture crowded every room. The December open house was mobbed anyway. Moore looked past the mess and saw a parlor-level unit with nearly 12-foot ceilings, a bowfront window, exposed brick in every room, a fireplace, and a small back deck, sitting between two parks (Hayes Park and the recently reopened Crite Park), and a short walk to Back Bay Station.

The rental-grade condition was an opportunity, he figured. Having renovated before, he knew what paint, refinished floors, and properly scaled furniture could do. And the listing price, set low in part because of those unflattering photos, was under his ceiling.
“What’s the catch here?” he remembered thinking.
That catch arrived quickly. The condo drew 12 offers, including all-cash competition. Moore’s agent, Brett Campbell of Gibson Sotheby’s International Realty, had done a deal with the seller’s agent before, and that track record helped Moore’s financed offer prevail. But winning meant going to $780,000 — $80,000 over asking, and past the top of his budget.
Then came a wrinkle Moore had never encountered: the unit was an investment property, and the sellers were rolling the proceeds into a 1031 exchange, making the entire sale contingent on their finding a replacement property, he said. Partway through negotiations, the property the sellers had identified fell through, pushing out the closing on Moore’s dream home. Open house to closing took roughly 90 days.
“Ride this ride. There are going to be highs and lows,” Moore said of his mindset at the time. “It might fall apart, and we just have to be okay with that, because the upside was still ultimately there.”

The unit was also tenant-occupied, with a lease running through the end of May — a problem since Moore’s lender required him to take occupancy within 60 days of closing. The sellers negotiated an earlier move-out with their tenants, but because the closing and lease still overlapped, Moore briefly became a landlord. On advicethat Massachusetts’ technical requirements around deposits, he didn’t collect a security deposit from the tenants, who were understandably unhappy about leaving early, and just hoped for the best.
The money
Moore’s down payment came from the sale of his Southie condo, but the rate environment for a mortgage stung.
He locked in at 6.6 percent — accepting that 2021 rates were “never coming back” — and that his purchasing power had shrunk accordingly. About nine months in, he refinanced into a five-year adjustable-rate mortgage at 5.75 percent. Between the refinance and the city’s residential exemption, which kicked in partway through the year, his monthly housing costs dropped by roughly $1,500.

Making a brownstone home
The first year delivered a full curriculum in brownstone ownership. The building’s shared pipes froze twice during an exceptionally cold winter, once leaving him without hot water for nearly two days during a snowstorm — “a memorable lesson in dripping the faucets when temperatures drop below 20 degrees,” he said.
The washer died; the delivery crew then discovered corroded shutoff valves that required a plumber before the new one could be hooked up. A declining backyard tree needed removal, another shared expense. Parlor-level living beside the front door came with a soundtrack of comings and goings.
The location, though, has over-delivered.
“I can be at the Pru in five minutes,” Moore said, and his commute is now a few blocks to Back Bay Station and four Orange Line stops to his office.

Before moving in, Moore painted every room, installed matching hardwood in the previously carpeted bedrooms, and refinished the floors in dark walnut. Since then, he has turned a cluttered nook off the kitchen into a proper dining room with a round table, an oversized mirror, and a dramatic pendant light, and transformed the second bedroom with a custom Murphy bed and a California Closets wardrobe into a guest room/office. Up next is the installation of ductless mini-splits, adding built-in wardrobes for the primary bedroom, and, over time, restoring the crown molding and mantel the unit lost somewhere along the way.
“I’m really glad I trusted my gut that the fundamentals were there,” Moore said. “This sounds cliché, but it’s been better than I expected.”

Advice for buyers
“Just accepting that these high rates mean you’re going to be paying a lot of interest. You can always refinance after the fact,” Moore said. “You likely will have to take on a fair amount of risk in the transaction. That’s just a reality in the market today. If you calculate the risk and how much you really have a tolerance for it, it ultimately is worth it — if the fundamentals are there.”
Address Newsletter
Our weekly digest on buying, selling, and design, with expert advice and insider neighborhood knowledge.