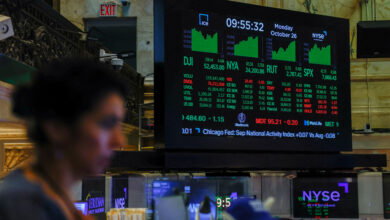

The Nasdaq Composite and S&P 500 finished lower on Monday, reversing early session gains as investors continued trimming exposure to technology equities and reallocating capital into broader market sectors. The tech-heavy Nasdaq dropped 1.07% to close at 25,164.32, while the S&P 500 shed 0.51% to settle at 7,541.40. Both major benchmarks had traded up as much as 1.4% and 1.1% respectively earlier in the day.
In contrast, the Dow Jones Industrial Average outperformed the broader market, advancing 213.67 points, or 0.41%, to close at 51,983.98. The Dow’s resilience was powered by gains in traditional industrial and retail equities, including Sherwin-Williams and Home Depot, which climbed nearly 6% and 3.6% respectively. Honeywell International, 3M, and Boeing each posted gains exceeding 2%.
Technology shares faced renewed selling pressure following a difficult week that logged significant losses, particularly for the Nasdaq, which suffered its worst performance since March 2025 amid growing scrutiny over artificial intelligence infrastructure spending. On Monday, Nvidia and Meta Platforms each dipped 1%, while Apple closed nearly 2% lower ahead of its post-bell earnings report. Oracle shares slumped 8% after the database software giant announced plans to issue $10 billion in common stock and $10 billion in senior notes to finance its ongoing AI buildout. Marvell Technology shares dropped almost 13% and Lumentum shed 18% following the announcement of Marvell’s $115 billion acquisition of Lumentum.

Despite short-term turbulence, market strategists noted that the underlying framework of the equity market remains stable. Chris Larkin, managing director of trading and investing at E-Trade, observed that the longer-term bullish narrative remains intact despite recent disruptions from energy prices, inflation, and geopolitical factors. Markets are also bracing for potential volatility triggers, including upcoming U.S. midterm elections where Democrats are widely expected to capture the House of Representatives while Senate control remains uncertain.
Energy markets experienced a sharp downturn on Monday, with Brent crude tumbling 7.63% to close at $104.77 per barrel, while U.S. West Texas Intermediate futures pulled back 7.36% to settle at $96.46. The sell-off in crude was driven by optimism surrounding potential diplomatic talks between the United States and Iran. Secretary of State Marco Rubio stated over the weekend that President Donald Trump has not made a decision to attack Iran and that Washington prefers a peaceful resolution. Iranian state media also reported that the country’s foreign minister indicated an agreement is possible if the U.S. demonstrates goodwill.
Economic data released on Monday provided mixed signals regarding domestic activity. The Commerce Department reported that U.S. construction spending in September fell 1.9%, marking the steepest monthly decline since April 2020 and missing economist forecasts for a 0.4% increase. The contraction was heavily driven by a 5.5% drop in residential spending, which outweighed a modest 0.6% rise in nonresidential outlays. Conversely, the Institute for Supply Management reported that its manufacturing index rose to 55.5 in October, a one-point increase that outpaced consensus estimates and signaled accelerated factory activity as production ramped up.