
rising borrowing – Mortgage and auto loan rates are hitting multi-year highs, forcing families like the Goldsteins to put major life milestones on indefinite hold.
Carrie Goldstein’s dream was simple: a house with enough character to match her family’s lifestyle. set in a walkable neighborhood where the front door led to more than just a sidewalk that goes nowhere. She found that vision in Rocky River, a suburb near Lake Erie, complete with a quaint downtown. But as she sat down to crunch the numbers, the math stopped her cold.
The mortgage payments for that dream house. paired with the reality of an 11-year-old car currently pushing 150. 000 miles. simply didn’t add up. Goldstein eventually unsubscribed from her real estate alerts. “It just became more and more disheartening when I did the math,” she says. “It’s just not in the cards.”.
Goldstein is navigating a landscape where the cost of borrowing has hit levels not seen in years. Mortgage rates have climbed to their highest point in nearly three years, currently averaging 7.28% for a 30-year fixed loan. For a median-priced home, that rate translates to roughly $900 more per month than the 3% rates common during the pandemic. This financial barrier is reshaping the market; existing home sales in August dropped 1.2% from a year earlier.
Behind these personal calculations lies a shift in the bond markets, where yields have surged to decades-high levels. These yields influence borrowing costs across the economy. pushing interest rates upward for everything from homes to cars and higher education. The situation is poised to tighten further following the Federal Reserve’s decision in September to raise interest rates. with signals that another hike may follow this year. These rate hikes are intended to cool consumer and business spending by making debt more expensive. but for individuals. the impact is immediate and visceral.
“If you need to borrow, boy, it’s really not a good time,” says John Diamond, senior director of the Center for Tax and Budget Policy at the Baker Institute.
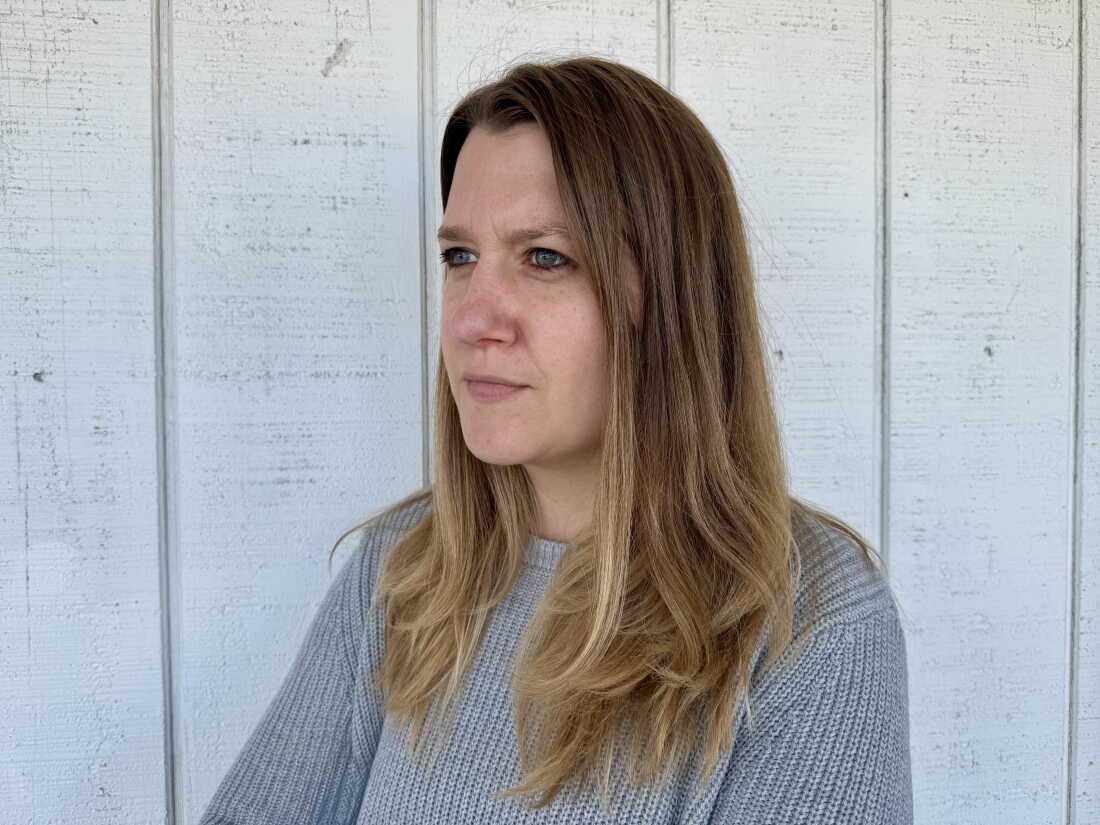
The strain is compounding for families already weathering years of high inflation. Beyond the housing market, auto loans have become significantly harder to manage. A four-year loan for a used car today carries an interest rate about three percentage points higher than it did at the start of 2022. For Goldstein. whose current vehicle requires repairs that are approaching the car’s total value. the monthly payments for a replacement are no longer sustainable. “You can’t go and get a car for $150 or $180 bucks anymore a month,” she notes.
The current cycle of financial pressure—rising mortgage payments. increased costs for student loans. and persistent inflation—is hitting households simultaneously. As the Federal Reserve’s quarter-percentage-point hike ripples through the economy. the cumulative effect of these costs is forcing many to delay essential purchases. For now. the dream of a new home and a reliable car remains deferred. caught in the widening gap between what families need and what the current economy allows.
mortgage rates interest rates economy housing market auto loans inflation Federal Reserve