
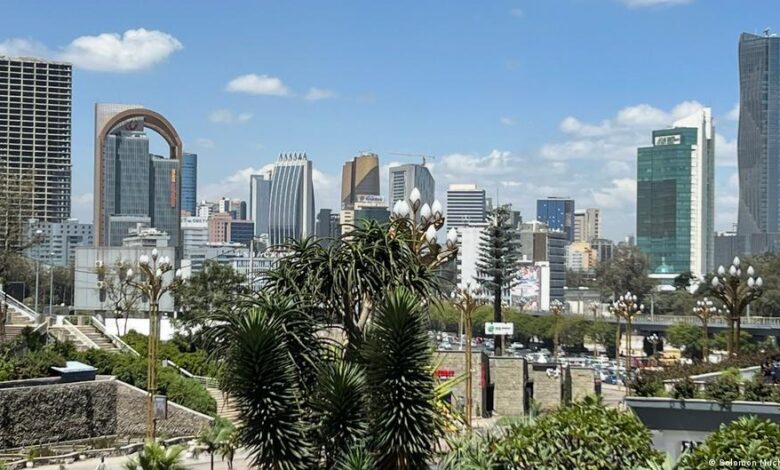
Ethiopia’s recent economic performance presents a striking paradox. Financial sector growth and large infrastructure projects have transformed the skyline of Addis Ababa, and the International Monetary Fund forecasts robust real economic growth of 9.2% for the 2025–26 fiscal year. Yet, this positive trajectory is increasingly shadowed by the threat of renewed fighting in the northern regions, mounting reconstruction expenses, and climate-induced crop failures that risk halting the nation’s broader economic recovery.
London-based financial analyst Abdulmenan Mohammed has cautioned against the compounding dangers of further escalation. “If there is a major conflict […] the current economic growth will not be sustainable,” he warned.

The country continues to grapple with the costly financial legacy of the 2020–2022 war in Tigray and surrounding areas, which inflicted widespread devastation on infrastructure, corporate production capacity, and agricultural output. A damage and needs assessment backed by the World Bank estimated direct physical destruction between November 2020 and December 2021 at more than $22.6 billion, with economic losses reaching approximately $6 billion. A subsequent multi-year reconstruction plan spanning 2023 to 2028 placed the total estimated funding requirement at roughly $19.7 billion, though full financing and timely completion remain uncertain.
Beyond direct physical damage, Mohammed notes that the earlier conflict triggered severe macroeconomic strain, including depressed economic output, soaring inflation, and acute foreign currency shortages. International trade conditions also suffered a blow when Ethiopia lost its duty-free export access to the United States under the African Growth and Opportunity Act in 2022.

Following the Pretoria peace agreement in November 2022, economic activity began to rebound. The IMF reported GDP growth of 7.2% for 2022–23 and 8.1% for 2023–24, projecting further expansions of 9.2% for both 2024–25 and 2025–26, driven primarily by agriculture, mining, and electricity generation. Economists emphasize that national GDP growth can continue if non-conflict sectors expand while other regions suffer, but high growth rates do not erase deep-seated structural vulnerabilities. Ethiopia defaulted on a Eurobond interest payment in late 2023, and the government relies on structural reforms backed by a 2024 IMF program to address persistent fiscal imbalances.
A renewed military escalation would place immediate pressure on public finances, forcing the state to divert scarce resources toward military personnel, equipment, and logistics at the expense of infrastructure, education, and social services. A prolonged conflict could also cause businesses to delay capital investments and prompt international donors to adopt a more cautious stance, leaving fewer public funds available for essential development projects like roads and energy grids.

Inflation remains a central economic hurdle, with the IMF forecasting an average rate of 11.7% for 2025–26. Mohammed suggests that intensified conflict would likely drive prices higher as the government resorts to increased domestic borrowing, which risks crowding out private sector credit access. Furthermore, military demands for foreign exchange to acquire imported equipment could restrict the availability of foreign reserves for private businesses attempting to buy imports, putting downward pressure on the birr exchange rate and raising costs for fuel and industrial inputs.
Vulnerability is particularly acute in the agricultural sector, where fighting frequently occurs in rural areas where farmers live and work. Insecurity around arable land, fractured transport networks, and shortages of agricultural inputs combine with poor seasonal rainfall to threaten harvests, lower farm incomes, and inflate food prices. The tourism and hospitality industries are similarly exposed, as security concerns and negative travel advisories deter visitors and reduce hospitality revenues.
Despite these domestic headwinds, there is currently no concrete evidence that international investors are actively withdrawing capital from Ethiopia to relocate to neighboring countries such as Kenya. Market observers point out that corporate location decisions depend heavily on broader governance metrics, tax administration, and public service reliability alongside immediate security conditions. Nevertheless, around 750,000 people remain internally displaced across the country as a consequence of past conflict, underscoring the deep social and economic stakes as the nation navigates its ongoing recovery.