

Silicon Valley has long operated under the assumption that whoever engineered the most advanced artificial-intelligence model would ultimately dominate the industry. However, rising capital expenditures required to build frontier models, coupled with falling token prices for end users, are reshaping the economics of the sector and shifting bargaining power toward established cloud infrastructure providers.
Anthropic is currently preparing for an initial public offering in November, targeting a $2 trillion valuation in what is expected to be a major test of investor appetite for the ongoing artificial intelligence boom. Ahead of the planned debut, the company informed investors that its third-quarter revenue reached $16.8 billion, representing a quarter-on-quarter growth rate of approximately 50%. While substantial, that figure marks a deceleration from a growth rate of 140% earlier in the year.
The slowdown has sparked intense debate among market observers, though financial analysts note that a 50% quarterly expansion still implies substantial annual scaling. The primary challenge lies in the sheer volume of new revenue required each quarter to maintain exponential trajectories, combined with escalating infrastructure costs. According to an August analysis published by Citadel Securities, developers face a widening economic gap as the computing power needed to train and run advanced models grows more expensive while usage prices decline.
Proponents of the current market trajectory often point to the Jevons paradox, suggesting that cheaper artificial intelligence will drive a dramatic increase in overall consumption, thereby sustaining demand for underlying compute resources. Yet survey data indicates shifts in enterprise purchasing habits that complicate that thesis. Findings published in September by Enterprise Technology Research, based on a survey of 200 companies, show that cheaper open-weight models now account for more than a third of enterprise token usage, up from 23% a year earlier. Survey respondents projected that share would climb to 41% over the following twelve months as more organizations opt for solutions that are deemed sufficiently capable rather than paying premium rates for top-tier frontier models.
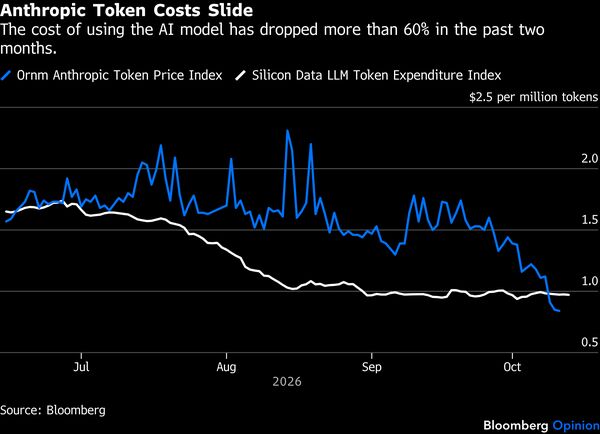
At the same time, major enterprise customers have begun adjusting their internal spending. Over the past year, prominent corporate clients including Microsoft and Meta Platforms have trimmed their internal use of Claude in favor of proprietary alternatives to curb rising token expenses. These cost-saving measures compound the financial pressures facing frontier developers, who collectively face projections of $1.3 trillion in capital expenditures on data centers, advanced semiconductors, and computing hardware through the end of 2030.
Against this backdrop, the structural advantage appears to rest with the major cloud computing trio of Microsoft, Alphabet, and Amazon. Shares among these technology giants have risen an average of 10% since the beginning of the year. Controlling the underlying infrastructure, customer relationships, and distribution networks, these established firms stand to profit regardless of whether enterprises deploy Claude, older iterations of OpenAI technology, or lower-cost open-weight models originating from overseas.
While a broader market correction could affect the technology sector given the enormous debt financing committed to artificial intelligence infrastructure and its subsequent impact on bond markets, cloud providers retain significant buffers. Their diversified revenue streams outside of artificial intelligence and established enterprise relationships provide resilience, allowing them to weather margin compression and outlast pure-play model developers as the market matures.


