

The Singapore dollar is increasingly capturing the attention of global investors as a viable funding currency for carry trades, offering an attractive alternative to the Japanese yen amid shifting monetary policies across Asia. Market strategists point to a combination of cheap borrowing costs, declining currency volatility, and subdued expectations for further currency appreciation as the primary drivers behind the shift.
The Monetary Authority of Singapore recently opted to keep its policy settings unchanged in an unexpected move following consecutive tightening rounds in April and July. This policy pause reinforced expectations that future currency gains for the Singapore dollar will remain limited. Simultaneously, substantial safe-haven inflows have entered Singapore, flooding local money markets and driving down forward-implied yields, which serve as a key measure of short-term borrowing costs.
This economic environment creates a dual advantage for carry trade participants, who typically borrow in low-yielding currencies to purchase higher-yielding assets elsewhere. Analysts note that low funding costs combined with minimal currency volatility reduce the risk that sudden exchange-rate fluctuations will erase the yields earned on overseas investments.
According to Abbas Keshvani, Asia macro strategist at RBC Capital Markets, funding in the Singapore dollar benefits from negative carry because the jurisdiction’s foreign exchange implied yields remain lower than those of most regional peers, alongside limited upside for the currency itself. In contrast, borrowing in the Japanese yen carries heightened exposure to potential policy normalization by the Bank of Japan.
Central bank divergences have sharpened the contrast between the two currencies. The Bank of Japan raised its policy rates by 25 basis points in September, and current swap markets indicate an 80% probability of another quarter-point rate increase by December. This hawkish trajectory has propelled the yen to a 2.7% gain against the U.S. dollar in the second half of the year, whereas the Singapore dollar has risen by 1.3% over the same period.
Data compiled across 38 developed and emerging-market currencies places the Singapore dollar’s three-month forward-implied yield at approximately 1.65%. This positions the currency among the least expensive funding options globally, alongside the yen and the Swiss franc.
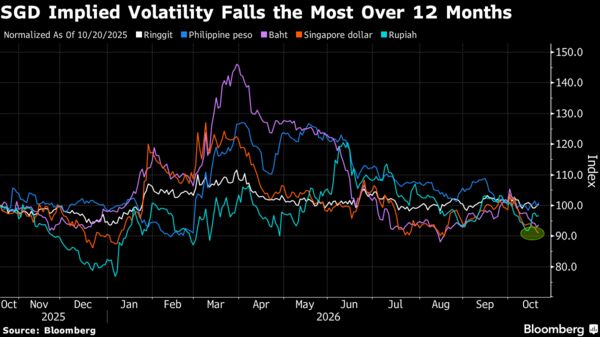
Furthermore, currency stability has improved significantly. Three-month option-implied volatility for the dollar-Singapore dollar pair has declined to 3.55%, marking the steepest drop over the past year among Southeast Asian counterparts.
Unlike many global central banks that rely on interest rate adjustments, the Monetary Authority of Singapore utilizes the exchange rate as its primary monetary policy instrument. The decision to leave the policy band’s slope unchanged this month signaled a strategic pause following earlier tightening measures, generating immediate reactions from major financial institutions.
Joey Chew, a strategist at HSBC Holdings Plc, noted in a client communication following the policy announcement that the market is likely to increasingly view the Singapore dollar as a regional funding currency, driven by ongoing downward pressure stemming from prevailing low interest rates.


