
Nearly eight months of war involving Iran have triggered one of the most severe energy shocks in recent decades, exposing a sharp divide between nations that absorbed the disruption with relative ease and those forced into painful economic and operational tradeoffs. Rather than depending on any single technology or policy, resilience has proven to stem from systems-level planning, long-term investment, and deliberate operational flexibility.
The global fallout demonstrated that the best-coping countries were not necessarily those with the most abundant natural resources, but rather those that engineered alternative pathways, redundancy, and flexibility into their energy architectures. China successfully navigated the shock by drawing on strategic reserves, utilizing alternative pipeline imports, and executing fuel switching. Meanwhile, the United States leveraged record domestic oil and gas production, regional storage capacity, and solar integration to bolster summer grid stability while maintaining secure North American supply chains. In highly electrified Norway, reliance on hydropower, heat pumps, electric vehicles, and infrastructure geographically removed from the conflict zone shielded the economy.
Conversely, emerging markets experienced severe strain. Bangladesh and Pakistan were forced to implement electricity restrictions and wide-ranging demand-reduction measures. Wealthier economies across Europe and Asia avoided outright shortages only by absorbing sharply higher spot prices for liquefied natural gas and alternative fuels. Analysts note that the defining boundary in the crisis ran not between net producers and net consumers, but between countries equipped with options and those with none.
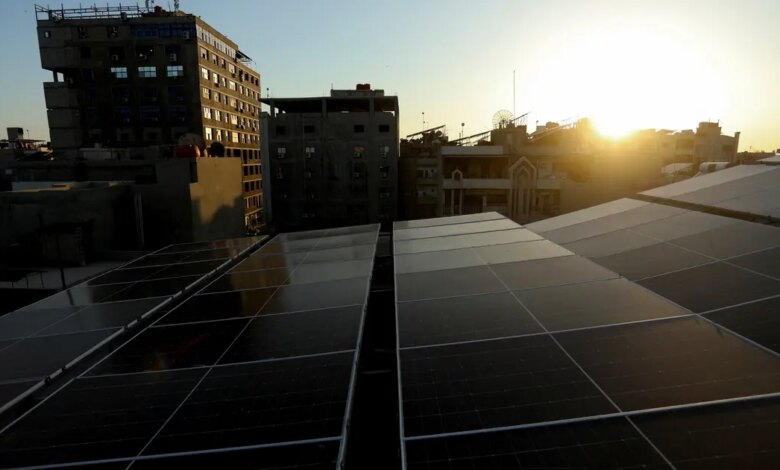
The conflict has underscored three foundational lessons for governments and financial markets moving forward. First, domestic electrons represent safer electrons. Shortening and securing the energy supply chain minimizes vulnerabilities, as energy produced, generated, or stored at home remains largely insulated from distant geopolitical chokepoints. While few nations can achieve total energy independence, all can reduce single points of failure. Solar power and energy storage have scaled rapidly due to favorable economics and technical maturity, while global demand shifts are prompting some producers to expand oil and gas output in regions with safer access to trade routes.
Simultaneously, the conflict has unlocked public and private capital for nuclear and geothermal energy. Nuclear power is receiving renewed attention as both an economic and national security pillar, offering reliable generation insulated from short-term geopolitical shocks. Small modular reactors are viewed as a potential path to supplying dependable power near military installations, advanced manufacturing hubs, and artificial intelligence data centers. In parallel, advancements in deep drilling and enhanced geothermal systems promise to expand access to round-the-clock power far beyond traditional geographic regions.
Second, electrification has transitioned from a purely climate-focused strategy into a core national security imperative. Every domestically produced electron reduces reliance on volatile global fuel markets, shifting the operational burden directly onto domestic power grids. The primary challenge is no longer merely generating sufficient electricity, but constructing the physical and digital systems required to deliver that power precisely when and where it is needed.
In the United States, however, these demands collide with aging infrastructure. The U.S. electric grid ranks among the largest globally, yet approximately 70 percent of transmission lines exceed 25 years of age, and the average large power transformer has been in service for nearly four decades. While demand for transformers has surged, domestic manufacturing capacity remains constrained; the country relies on a single domestic producer for the specialized electrical steel required for transformer cores. In 2025, foreign suppliers accounted for 80 percent of power transformer supply and 50 percent of distribution supply components.
Workforce attrition compounds these physical bottlenecks. The U.S. power sector faces a projected need for more than 500,000 additional workers by 2030, a demand arriving simultaneously with the retirement of hundreds of thousands of experienced employees. Furthermore, regulatory permitting delays stall major infrastructure projects for four to five years, holding up approximately $1.5 trillion in investment. These persistent delays have galvanized political action, resulting in significant state-level legislation and a bipartisan permitting reform bill proposed in the Senate.
Third, addressing near-term energy security challenges cannot rely exclusively on multi-year infrastructure projects such as new power plants or massive transmission corridors. Because immediate constraints are pressing, experts emphasize maximizing the utility of existing assets. Long-duration batteries can capture surplus electricity and release it during deficits, while grid-enhancing technologies increase transmission capacity, reduce congestion, and boost asset efficiency. Additionally, smart-grid software and demand-management tools can dynamically shift consumption away from peak stress periods without requiring new physical construction. The overarching takeaway from the crisis is that the most successful energy systems of the coming decade will not just generate more power, but will store it more effectively, transport it more efficiently, and protect it more securely.


