
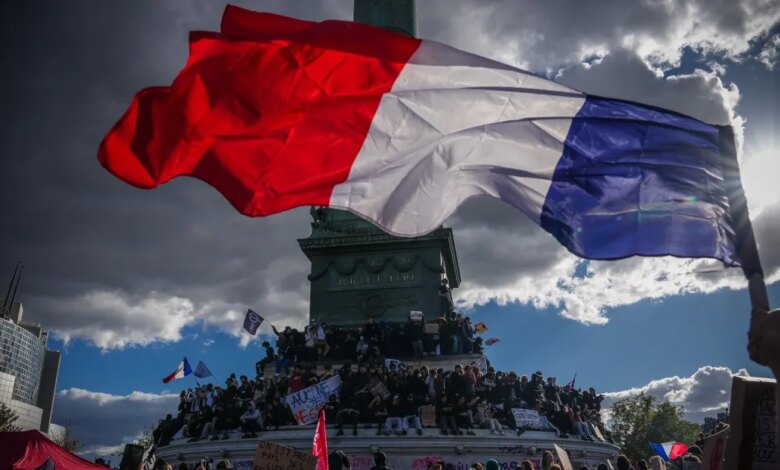
France is confronting its highest borrowing costs in nearly a quarter of a century as financial markets demand elevated returns for holding government debt. This upward pressure on bond yields unfolds against a backdrop of severe social unrest, with hundreds of thousands of protesters taking to the streets to oppose proposed budget cuts and demand increased spending on public services and cost-of-living relief.
National debt has climbed to its highest point since the immediate aftermath of World War II, approaching 120 percent of gross domestic product. France’s 10-year bond yield has risen by more than 130 basis points since June, topping 4.9 percent. These soaring yields consume an expanding share of tax revenues that might otherwise support essential public sectors.
Market anxiety is driven less by the absolute volume of debt than by the trajectory of public finances and a fragmented political system struggling to govern effectively. In the National Assembly, Prime Minister Sébastien Lecornu faces a difficult legislative battle to pass a budget for next year that incorporates 54 billion euros, equivalent to about $61bn, in savings. Opposition figures Marine Le Pen of the far-right National Rally and Jean-Luc Mélenchon of the far-left France Unbowed have rejected the proposals, though the government retains the constitutional option to bypass parliament.
Economists point out that France’s economic numbers are not drastically worse than those of other nations, but the political gridlock prevents the implementation of a coherent budget that addresses debt sustainability. Total national debt stands at approximately 3.6 trillion euros, or $4 trillion, representing roughly 119 percent of GDP compared with 98 percent in 2019. More pressing for investors is the national deficit, projected to reach 5.4 percent of GDP in 2026, well above the European Union average of slightly over 3 percent.
France maintains one of the largest public sectors in the developed world, with government spending accounting for approximately 57 percent of GDP, second only to Finland among Organisation for Economic Co-operation and Development countries. Public pensions consume about 14 percent of GDP, an expenditure that faces upward pressure from a shrinking working-age population. Although President Emmanuel Macron has long advocated for pension reforms to alleviate the fiscal burden, previous attempts have stalled amid intense political resistance.
Compounding these fiscal challenges is a prolonged period of sluggish economic growth. The French economy expanded by only 59 percent of the OECD average between 2000 and 2025, with GDP forecast to grow by just 0.4 percent following a 0.9 percent expansion in 2025. While European peers successfully normalized their fiscal positions after the pandemic, public spending growth in France has consistently outpaced revenue dynamics.
Comparative analysis shows that nations with higher debt-to-GDP ratios, such as the United States, Japan, and Italy, manage their obligations through distinct structural advantages. The U.S. benefits from the dollar’s reserve currency status, Japan relies heavily on domestically held debt and ultralow interest rates, and Italy maintains a smaller budget deficit of around 3 percent. Meanwhile, France faces increased competition for capital within the euro-denominated bond market as Germany issues more debt and Italy and Spain strengthen their fiscal positions.
Economists caution that while a French default remains an unrealistic scenario, delaying fiscal adjustments risks a profound loss of economic credibility and increases long-term vulnerability if corrective measures are postponed indefinitely.


